Different companies. Different approaches. One autonomous future.
By now, most of you will have seen the media coverage surrounding Tesla’s Cybercab launch: a purpose-built robotaxi with no steering wheel and no pedals, already carrying passengers autonomously in Texas and expanding rapidly.
It feels like the beginning of something new. But the robotaxi race has been underway for much longer than most people realise.
Waymo is already operating at meaningful scale across multiple US cities, while China’s Baidu, Pony.ai and WeRide have spent years building large commercial fleets and dense multi-city networks. XPeng is now entering the race with its own purpose-built L4 robotaxi.
The race has entered a new phase. It is no longer simply about proving autonomy works. It is about who can scale it safely, cheaply and almost everywhere.
Economics
Baidu Apollo Go, Pony.ai, and WeRide are not running pilots. They are running systems. Large fleets, millions of rides, and rapidly falling costs. The conversation has moved from capability to economics.
Early pricing signals show substantial differences between markets. Tesla’s early US robotaxi fares remain well above the ultra-low pricing seen in some dense Chinese deployments, while Waymo fares also vary considerably by city and trip. Baidu Apollo Go has demonstrated exceptionally low pricing in markets such as Wuhan, with Pony.ai and WeRide also competing aggressively in China.
The gap is not marginal, but neither is it a clean comparison of underlying operating costs. Fares reflect different market conditions, subsidies, promotions, labour costs, utilisation and rollout strategies.
These low fares are emerging in dense, highly optimised urban environments, supported by favourable regulation and, in some cases, subsidised rollout phases. Lower labour costs, including remote safety monitoring, also contribute. These conditions are not directly comparable to early-stage deployments in sprawling US cities like Austin.
But low fares and disruption do not automatically mean high profits. As robotaxis move from demonstration to commercial scale, an increasingly important question is who actually captures the economics?
Vehicle manufacturers, autonomy providers, ride-hailing platforms and fleet owners occupy different parts of the value chain and carry very different risks. As fleets scale and competition intensifies, fares and margins could eventually be driven sharply lower.
Robotaxis could profoundly disrupt transport while some of the businesses financing and operating those vehicles earn mediocre returns.
Being right about the disruption doesn’t necessarily mean being on the right side of the economics. You can correctly predict the future and still lose money by backing the wrong part of the value chain.
Hardware
On the hardware side, Tesla’s Cybercab target under $30,000 is compelling. But China is not behind here either. Baidu’s RT6 platform is already around that level, purpose-built for autonomy and designed for mass deployment. Pony.ai and others are rapidly driving costs down through iteration and scale. The idea that China is trailing on vehicle economics no longer holds. They are already producing at the level Tesla is aiming for.
Tesla’s potential cost advantage therefore needs some qualification. Cybercab could have a substantial vehicle-cost advantage over Waymo, particularly if Tesla achieves its sub-US$30,000 target. But that advantage is far less obvious against China, where purpose-built L4 vehicles are already approaching similar price points while carrying more extensive sensor suites.
Tesla may have a major cost advantage over Waymo. It does not necessarily have one over China.
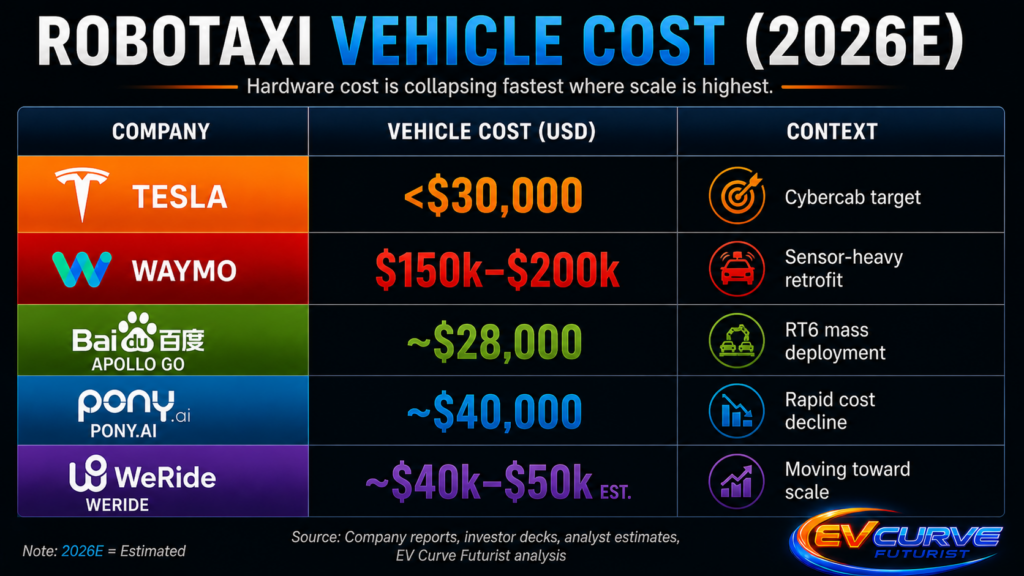
Caption: Hardware is no longer the bottleneck. Purpose-built autonomous vehicles in China are already approaching mass-market price points, matching or undercutting Western targets before full-scale rollout.
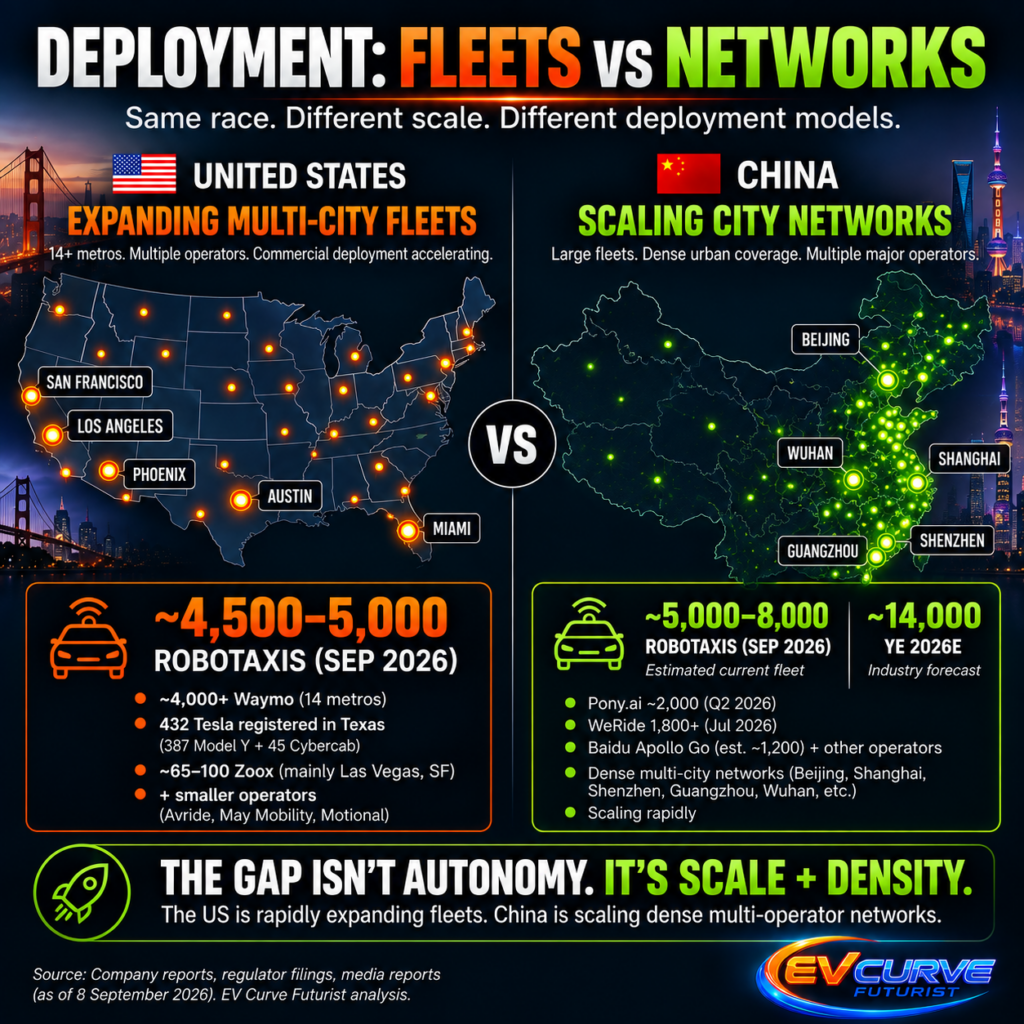
Caption: The difference is no longer pilots versus deployment. Both the US and China now operate commercial robotaxi fleets at meaningful scale. The emerging distinction is density and network structure: the US is rapidly expanding multi-city fleets, while China is scaling dense networks across multiple competing operators.
Deployment
The real gap now shows up less in whether robotaxis are being deployed and more in how they are being deployed. The US has moved well beyond pilot scale. Waymo alone operates roughly 4,000 vehicles across 14 metros, while Tesla, Zoox and smaller operators are adding to a US passenger robotaxi fleet of roughly 4,500–5,000 vehicles as of September 2026.
China’s advantage is different. It is building dense, multi-operator city networks. Current fleet numbers are harder to pin down because reporting is fragmented, but disclosed fleets and industry estimates suggest roughly 5,000–8,000 robotaxis are operating today, with industry forecasts pointing toward around 14,000 by the end of 2026.
Pony.ai had reached nearly 2,000 robotaxis by mid-year and is targeting more than 3,500 by year-end. WeRide has more than 1,800 robotaxis, while Baidu Apollo Go continues to operate one of the world’s largest networks across dozens of cities. Add DiDi, AutoX, Ruqi and other operators, and the distinction becomes clearer.
The US is no longer experimenting, and China’s advantage is no longer simply about having more vehicles. The emerging difference is network structure: China is concentrating multiple competing operators within the same urban markets, potentially accelerating utilisation, price competition and service expansion.
The field is getting more crowded too. XPeng is moving into purpose-built L4 robotaxis, bringing another vertically integrated Chinese EV manufacturer into the race. That matters because XPeng can combine autonomy development with automotive-scale manufacturing and China’s extraordinarily competitive EV supply chain.
At the same time, China’s robotaxi industry is moving beyond China. WeRide, Pony.ai, Baidu and others are expanding or preparing deployments across international markets, particularly Europe and the Middle East. That introduces a much harder test: different roads, regulations, labour costs, consumer expectations and political environments.
The next test isn’t whether China’s robotaxi model works in China. It’s whether its scale and economics travel.
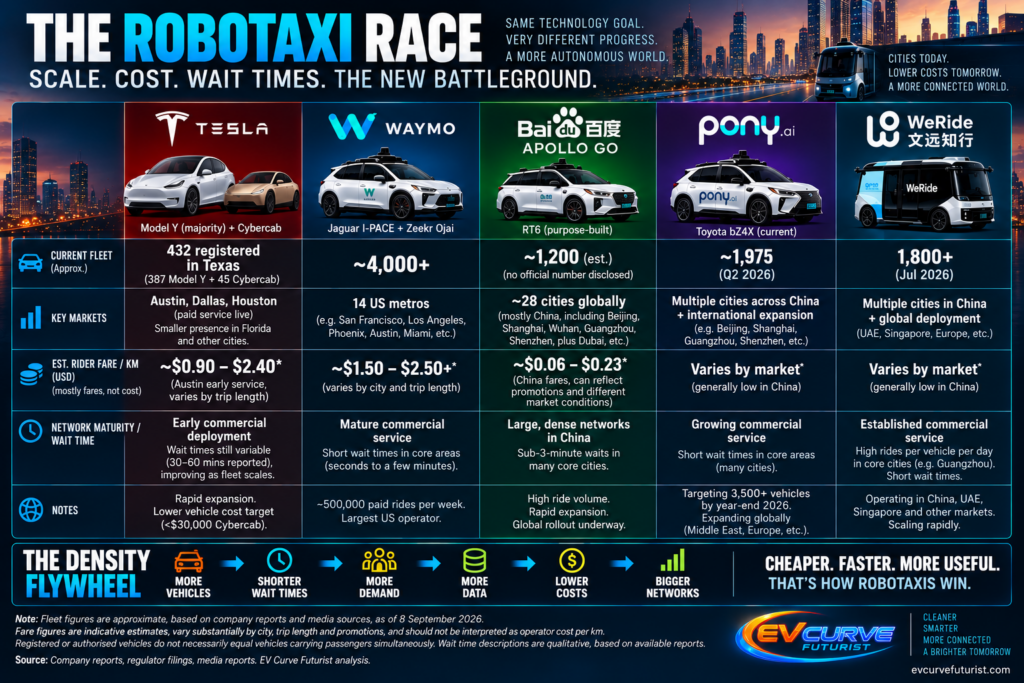
Caption: The robotaxi race is shifting from autonomy alone to economics and network performance. Fleet density drives shorter wait times, higher utilisation and lower costs, creating a flywheel that can accelerate adoption. The winners may not simply be those with the best autonomous driving technology, but those that can deliver the cheapest, fastest and most useful service at scale.
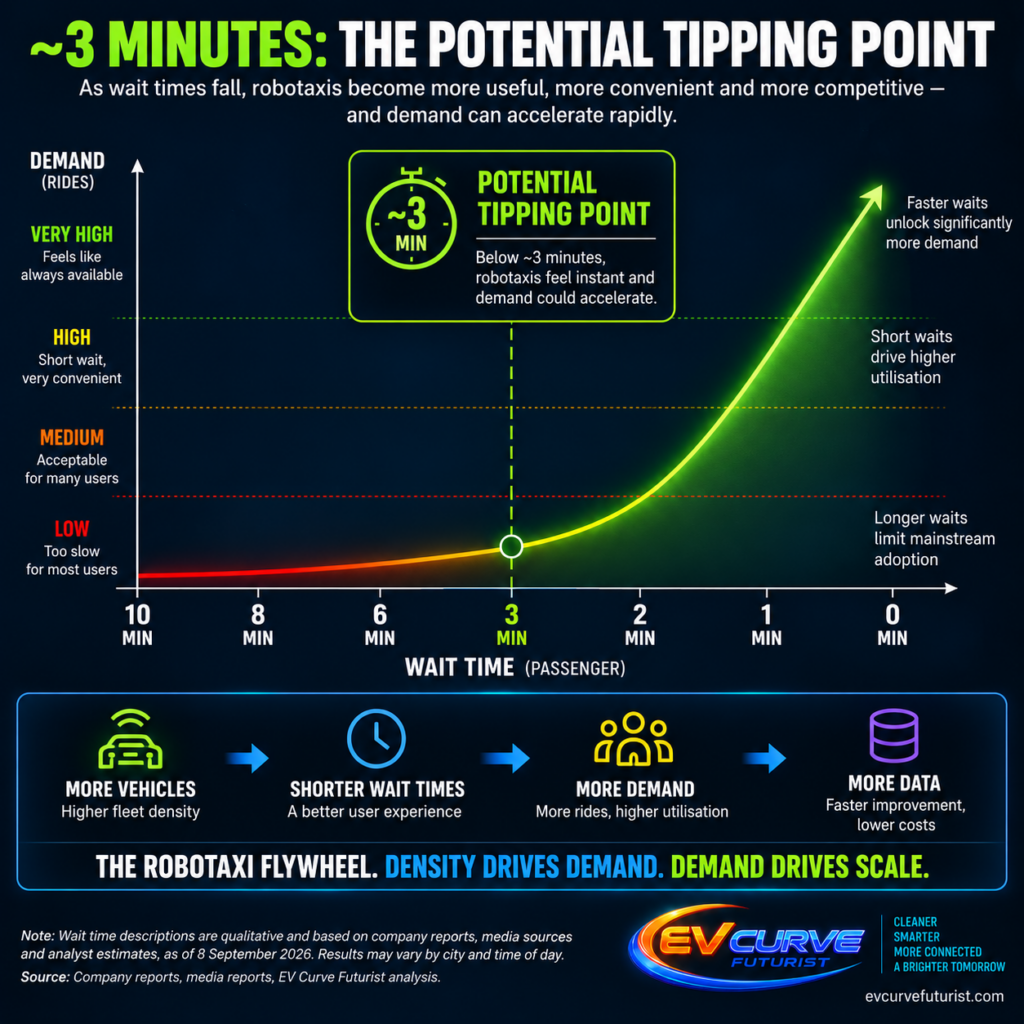
Caption: Shorter wait times are a key driver of robotaxi adoption. As fleet density and coverage improve, waiting falls and the service becomes increasingly convenient, driving higher demand, utilisation and data generation. Sub-three-minute waits could represent an important tipping point where robotaxis begin to feel effectively “on demand”, but the timing and impact will vary by market.
Density
Robotaxis do not win on autonomy alone. They win on density. More vehicles reduce wait times. Lower wait times increase demand. Higher demand generates more real-world data. More data improves models. Better models reduce cost. Lower cost drives more adoption.
This is the flywheel.
I suspect sub-three-minute wait times could become an important tipping point. That is where robotaxis may begin to feel less like a scheduled ride and more like transport that is simply there when you need it. China is already moving toward that threshold in some dense urban zones, while the West is still building toward it.
Technology
On the technology side, the industry remains split between two broad approaches. Waymo, Baidu, Pony.ai and WeRide continue to deploy multi-sensor systems combining cameras with lidar and radar to maximise redundancy and reliability. Waymo, for example, argues that the complementary strengths of cameras, lidar and radar are important for handling the long tail of difficult real-world conditions.
Tesla has taken a different path. Its vision-first approach bets that sufficiently capable AI, trained on vast amounts of real-world driving data, can ultimately generalise across environments without relying on lidar or highly detailed maps. If successful, that could reduce hardware complexity and potentially make autonomy easier and cheaper to scale across new cities and countries.
But Tesla is no longer alone in pursuing that philosophy. XPeng’s GX Robotaxi also uses a pure-vision system without lidar or HD maps, powered by its VLA 2.0 architecture. XPeng says VLA 2.0 was designed from the ground up for L4 autonomy, with a unified architecture spanning both L2 and L4, while the GX carries four Turing AI chips delivering 3,000 TOPS of onboard compute.
That makes XPeng particularly interesting. It is pursuing some of the same generalisation-first ideas as Tesla while simultaneously developing a purpose-built L4 robotaxi. XPeng continues to use different sensor strategies elsewhere in its vehicle range, but its Robotaxi architecture represents a deliberate move toward pure vision and reduced dependence on pre-mapped environments.
The debate is therefore becoming less binary. It is no longer simply vision versus lidar, or generalisation versus geofencing. The practical question is which combination of AI, sensors, compute and deployment strategy can scale faster, safer and cheaper across increasingly diverse real-world environments.
Safety data remains uneven across regions. Disengagement rates, incident reporting standards and transparency differ, making direct comparisons difficult. Chinese operators have reported improving performance over time, but methodologies vary considerably between jurisdictions and companies, making apples-to-apples comparisons difficult. Large-scale commercial deployment nevertheless becomes an increasingly important form of real-world validation.
Remote safety operators are another factor. Centralised monitoring can improve near-term reliability and economics, particularly where labour costs are lower, but continued dependence on human oversight could become a bottleneck as fleets grow toward very large-scale autonomous operation.
So far, the strongest evidence of commercial L4 deployment comes from systems optimised and validated for defined operating environments. But Tesla is no longer alone in betting heavily on generalisation. XPeng’s Robotaxi is now pursuing a similar pure-vision, no-HD-map path while building specifically for L4 deployment. That makes the next phase particularly interesting: whether generalised autonomy can eventually match the reliability of today’s constrained L4 systems without inheriting their geographic limitations.
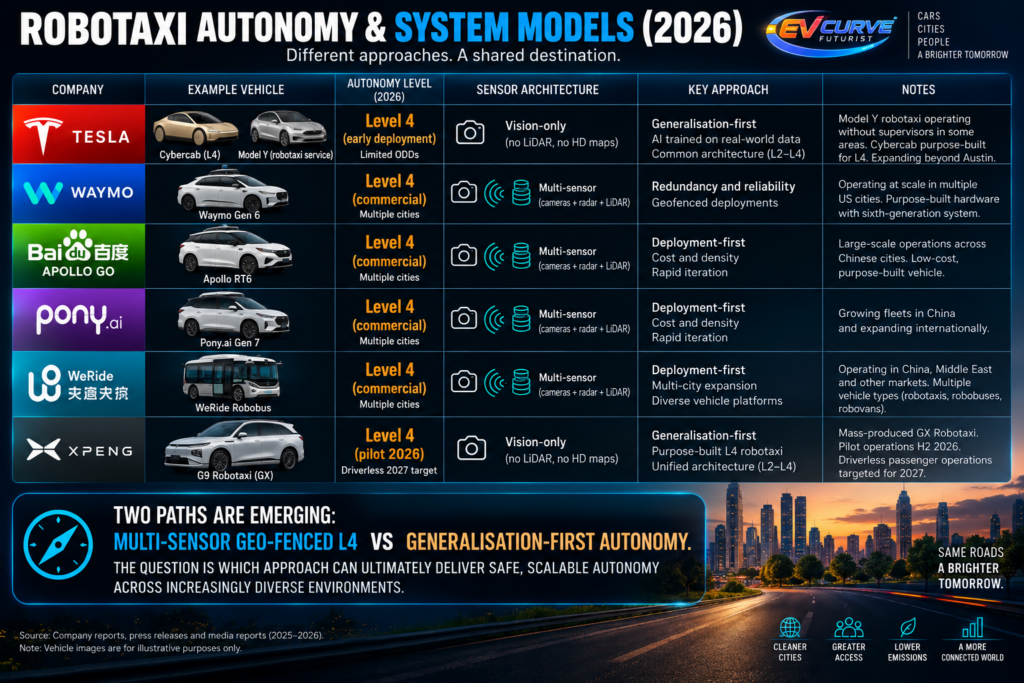
Caption: Two broad autonomy strategies are emerging. Waymo, Baidu, Pony.ai and WeRide rely on multi-sensor systems and defined operating domains, while Tesla and XPeng are pursuing vision-first architectures aimed at broader generalisation. The question is which approach can ultimately deliver safe, scalable autonomy across increasingly diverse environments.
Geopolitics
There is also a geopolitical layer. US restrictions on advanced semiconductor exports to China may influence long-term AI training and compute access. China’s domestic supply chain push could offset some of these constraints over time, but the balance of compute, policy, and capital will shape how fast each system scales. The real question is which can translate deployment into sustainable economics across different environments.
But geopolitics increasingly cuts both ways. As Chinese robotaxi companies expand internationally, another question emerges: will Western governments allow Chinese autonomous vehicles and autonomy technology to scale inside their markets?
Europe will be particularly important. Regulatory approval for commercial L4 operation, cybersecurity, vehicle data, privacy and potential trade restrictions could all influence how quickly Chinese platforms expand. Europe may become one of the most important battlegrounds between Chinese and Western autonomy ecosystems.
The technology may increasingly be capable of crossing borders faster than regulation allows it to.
Timeline
The tipping point is likely not immediate, but it is approaching. The next 12–24 months should tell us whether robotaxis are moving from early commercial deployment into genuine transport networks.
In China, the key transition is from thousands of vehicles operating across multiple cities to dense fleets capable of delivering consistently short wait times, high utilisation and sustainable economics. If current trends hold, major urban markets such as Wuhan and Shenzhen could begin reaching those conditions before 2027. Sub-three-minute wait times would be particularly significant, because that is where robotaxis begin competing not simply with taxis and ride-hailing, but with the convenience of private car ownership.
Outside China, the timeline may be determined as much by regulation as technology. Chinese operators are beginning to expand internationally, while Tesla, Waymo and others are pushing into additional markets. Europe and the Middle East will be important tests of whether systems developed in China or the US can reproduce their performance and economics under different road conditions, regulations and labour costs.
The period from 2027 to 2030 could therefore mark the transition from city-by-city deployments to competing regional and eventually international networks. By then, the important measures may no longer be autonomous miles or demonstration fleets, but rides per vehicle, utilisation, wait times, cost per kilometre, geographic coverage and sustainable margins.
The race is no longer about who deploys first. It is about who reaches the flywheel first, and whether that scaling advantage becomes difficult for competitors to reverse.
The Disruption
The real disruption is not one robotaxi company defeating another. It is what all of them collectively do to the industries built around humans operating vehicles.
Waymo, Tesla, Baidu, Pony.ai, WeRide, Zoox, XPeng and others do not all need to win. Enough of them simply need to succeed.
The first and most obvious targets are taxis and human-driven ride-hailing. As autonomous fleets scale, wait times fall and the cost of the driver disappears, robotaxis will compete aggressively on both price and convenience. The platforms themselves can survive and thrive. Uber and others can evolve from coordinating human drivers to aggregating autonomous fleets. The platform survives. The human-driver business model gets disrupted.
The employment implications are enormous. Taxi and rideshare drivers are only the beginning. The same underlying technologies are advancing into trucking, freight, delivery, buses and other forms of road transport. Autonomy will extend further into shipping, rail and aviation, progressively reducing the human labour required to move people and goods.
To be clear, I’m not cheering for those job losses. Quite the opposite. I’m simply describing where the technology and economics are taking us. Pretending the disruption isn’t coming won’t protect the people whose livelihoods are exposed to it. We should be thinking now about how workers transition, what new jobs replace the old ones, and how the enormous productivity gains from automation are shared.
The transition will occur at different speeds across industries and countries. Regulation, safety requirements, geography and economics will determine which markets move first. But the direction is clear: humans are progressively being removed from the routine task of operating vehicles.
By around 2030, the disruption of human-driven taxis and rideshare will be impossible to ignore in leading markets. Trucking, freight and other transport sectors will follow on their own timelines as autonomous technology becomes cheaper, safer and more capable.
And the disruption doesn’t stop with transport jobs. Once autonomous fleets become cheap, ubiquitous and available within minutes, they begin competing with something much larger than taxis and rideshare:
Private car ownership itself.
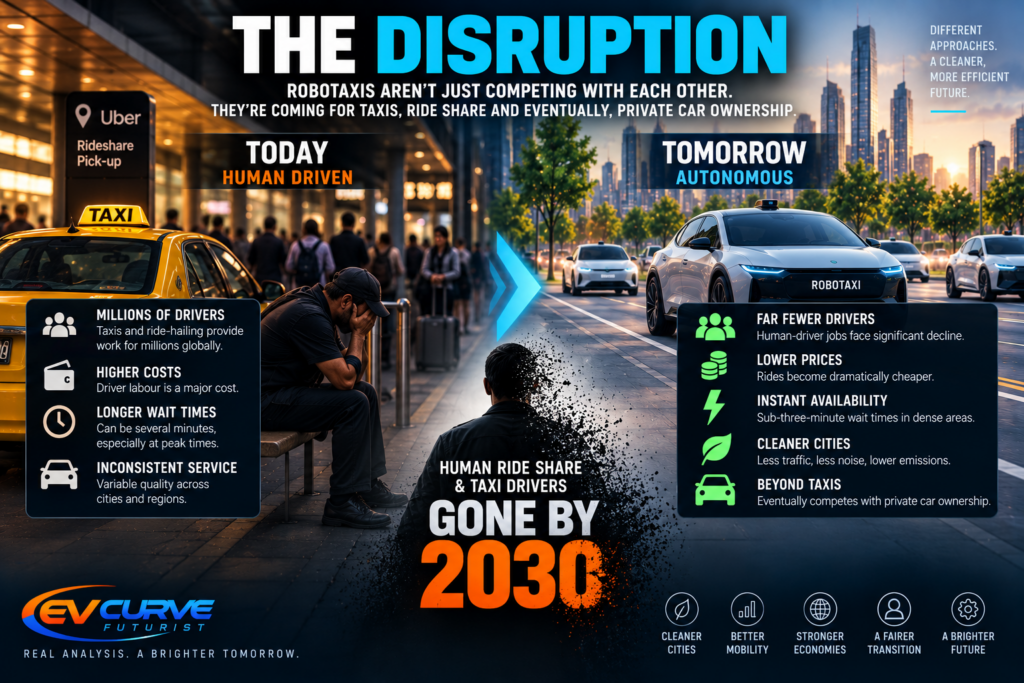
Caption: Robotaxis are only the beginning. As autonomous systems scale, the disruption will spread from taxis and rideshare into trucking, freight, delivery and eventually much of transport. I’m not cheering for the job losses, but the direction is increasingly clear: humans are progressively being removed from the routine task of operating vehicles.
What to watch in 2026–2027
- Wuhan and Shenzhen robotaxi wait times approaching sub-three minutes
- Tesla Cybercab production ramp versus Baidu RT6 volumes
- XPeng’s Robotaxi scale-up from production into commercial L4 deployment
- Pony.ai reaching 3,500+ vehicles and continuing to drive total robotaxi hardware cost down
- Chinese global expansion, particularly Europe, the Middle East and other international markets
- Whether Chinese operators can reproduce their China economics overseas
- European and UK regulatory approvals moving from testing toward commercial driverless operation
- Expansion beyond dense urban ODDs into increasingly difficult environments
- Utilisation and revenue per vehicle, not merely fleet size
- Robotaxi unit economics and who actually captures the margin
- Cybercab’s real production cost versus Chinese purpose-built L4 vehicles
- Regulatory or trade barriers aimed specifically at Chinese autonomous vehicles and autonomy technology
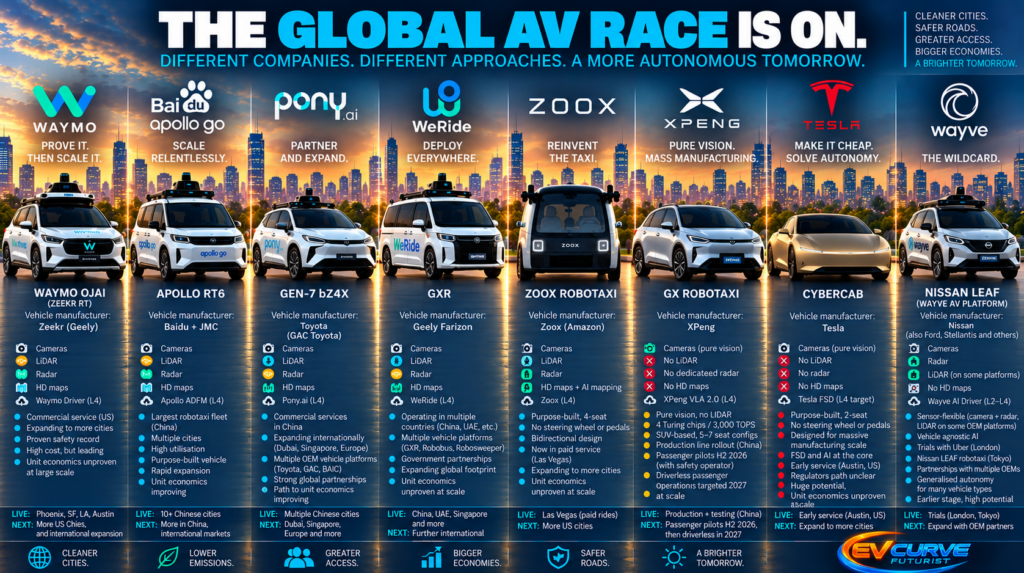
Caption: The global AV race is no longer a two-company contest. Waymo, Baidu Apollo Go, Pony.ai, WeRide, Zoox, XPeng, Tesla and Wayve are pursuing different combinations of autonomy, hardware, manufacturing scale and deployment. The destination may be similar, but the paths are increasingly different.
The Real Race
Tesla is pursuing a generalised autonomy path that could, if successful, leapfrog geofenced systems. Much of China’s robotaxi industry has taken a deployment-first approach, optimising for cost, density and rapid iteration within defined zones.
But that distinction is beginning to blur. XPeng has also embarked on a path toward generalised autonomy, while simultaneously developing purpose-built L4 robotaxis. If successful, it could combine some of Tesla’s generalisation-first philosophy with the manufacturing scale, hardware integration and deployment advantages emerging from China.
Increasingly, then, this isn’t simply Tesla versus Waymo, or even America versus China. It is a global competition between autonomy platforms, vehicle manufacturers, supply chains and regulatory systems. The winner may not be the company with the most impressive technology, but the ecosystem that can deploy it safely, cheaply and almost everywhere.
Some are scaling within constraints. Others are attempting to remove them. Increasingly, some are trying to do both.
The outcome will not be decided by capability alone. It will be decided by which approach converges on low cost, high density and broad applicability first.
That is the real race.
Sources
- Reuters – Driverless future gains momentum with global robotaxi deployments
- Reuters – China tightens oversight after autonomous vehicle incidents
- Apollo Go / Wuhan pricing context (Robotaxi overview)
- Pony.ai cost reductions and AV economics (Nature/industry summary)
- Waymo / AV safety performance (peer-reviewed analysis)
- Market comparison of US ride-hailing pricing vs China robotaxi costs
- XPeng – Robotaxi / VLA 2.0 and L4 autonomous driving strategy
- Pony.ai – 2026 robotaxi fleet expansion and Gen-7 mass production
- Pony.ai – Robotaxi unit economics and hardware cost reductions
- WeRide – Global L4 fleet and international expansion
- WeRide / Uber – European robotaxi expansion
- Reuters – Tesla Cybercab rollout and regulatory pathway